You made it. The short sale is over.
You’re relieved. The financial burden is lifted from your shoulders. Renting is okay, but you wonder how long before purchasing a new home.
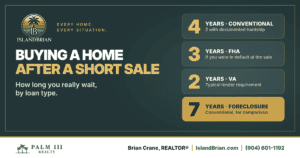
Buying a home after a short sale is possible sooner than most Florida sellers expect. The wait runs from about two to four years depending on the loan you apply for, and each program has an exception that can shorten it. A foreclosure can lock you out of a conventional loan for seven.
That difference is one of the strongest reasons to deal with a mortgage you can’t keep before the lender deals with it for you. Here is what each loan type requires, what shortens the wait, and what to do with the time.
Short sale waiting periods at a glance
| Loan type | Standard wait | What can shorten it |
|---|---|---|
| Conventional (Fannie Mae) | 4 years | 2 years with documented extenuating circumstances |
| FHA | 3 years if you were in default at the sale | May not apply if you paid on time for the 12 months before the sale |
| VA | About 2 years, set by lenders | Some lenders waive it with 12 months of on-time payments |
The clock starts on the day your short sale closes, not the day you listed or the day the lender approved it. Keep your closing statement. Your next lender will ask for that date.
Conventional loans: four years, or two with documented hardship
Fannie Mae’s Selling Guide requires a four-year waiting period after a short sale, which it calls a pre-foreclosure sale. The same four years applies to a deed in lieu of foreclosure.
The exception is extenuating circumstances. If you can document that the short sale came from an event outside your control, the wait drops to two years. Think job loss, a serious illness or the death of a wage earner, and expect to prove it with paperwork: termination letters, medical bills, tax returns showing the income drop.
Compare that with a foreclosure. Fannie Mae requires seven years after a completed foreclosure, or three with extenuating circumstances and added restrictions. On a conventional loan, a short sale gets you back to the table three years sooner.
FHA loans: three years, unless you stayed current
HUD’s rule is that a borrower who was in default at the time of the short sale is not eligible for a new FHA loan for three years from the sale date.
There are two ways around that:
- You were current when you sold. If every mortgage payment in the 12 months before the short sale was made in the month it was due, the three-year rule may not apply to you.
- The default was beyond your control. A lender can make an exception when the default came from something like the death of the primary wage earner or a long uninsured illness, and your credit was in good shape before it happened.
Most short sale sellers have missed payments by the time they close, so plan on three years. If you are underwater but still paying, though, the first exception is worth knowing about before you skip a payment on someone’s advice.
VA loans: no VA waiting period, but lenders set one
I’m a veteran myself, so I want fellow veterans to get this part right.
The VA does not set a fixed waiting period after a short sale. The two years you will hear quoted is a lender requirement, and it varies. Some lenders shorten or waive it if you made every payment in the 12 months before the sale.
Two more points for veterans:
- Your entitlement may be reduced. If the VA paid a claim on the loan you sold short, that part of your entitlement stays tied up until the loss is repaid. Any entitlement you have left may still be enough for your next purchase.
- The short sale has its own VA process. On a VA loan it is called a compromise sale. I cover it in my guide to VA compromise sales.
Because the two-year figure comes from lenders and not the VA, ask the VA lender you plan to use what their rule is before you count on a date.
What decides whether you qualify when the wait ends?
The waiting period only makes you eligible to apply. Approval depends on what you did during it. Lenders look at three things.
Your credit since the sale. A short sale can stay on your credit report for up to seven years, but its weight fades as newer history builds on top of it. Late payments after the short sale hurt far more than the short sale itself.
Your paperwork. Keep the short sale approval letter, the closing statement and the documents that prove your hardship. The approval letter also shows how the lender treated any unpaid balance, which a new lender will ask about. If you are not sure what yours says, read how lenders handle the shortfall at a short sale closing.
Your income and savings. The same rules as any buyer: steady income, a down payment and manageable debt.
Before you close on a short sale: forgiven mortgage debt can now count as taxable income. A tax bill you did not plan for can drain the savings you need for your next down payment. See short sale taxes in 2026 and talk to a tax professional first.
How to use the waiting period
- Pay everything on time. Rent, car, cards. Twelve clean months is the minimum most lenders want to see. More is better.
- Keep one or two credit lines open and low. You need active accounts reporting good history, not a closed file.
- Save for the down payment. A larger down payment offsets a thinner credit file.
- File your documents now. Hardship proof is easy to gather today and hard to find in three years.
- Talk to a loan officer a year early. They can tell you which program fits and what to fix while there is still time.
Common questions
How long after a short sale can I buy a house?
About two years with many VA lenders, three years with FHA if you were in default at the sale, and four years with a conventional loan. Each has an exception that can shorten the wait.
Is the wait shorter than after a foreclosure?
For a conventional loan, yes: four years after a short sale against seven after a foreclosure.
Does the waiting period start when I list the home?
No. It starts on the date the short sale closes.
Can I rent in the meantime?
Yes. A record of on-time rent payments also helps your next mortgage application.
Thinking about a short sale in Nassau or Duval County?
How you sell affects how soon you can buy again. I am a veteran and a Certified Short Sale Specialist with Palm III Realty in Fernandina Beach, and I work with homeowners across Amelia Island, Nassau County and Duval County who owe more than their home is worth.
Call or text me at (904) 601-1192, or contact me to set a time to meet using my Calendy IslandBrian.com. The conversation is private and costs nothing.
This article is general information, not lending, legal or tax advice. Waiting periods reflect program guidance reviewed in October 2026. Lenders can add stricter requirements, and rules change. Confirm your situation with a licensed loan officer.
Sources: Fannie Mae Selling Guide B3-5.3-07; HUD Mortgagee Letter 09-52; VA: trouble making payments on a VA-backed loan.